Subtotal ₹0.00



Email :11
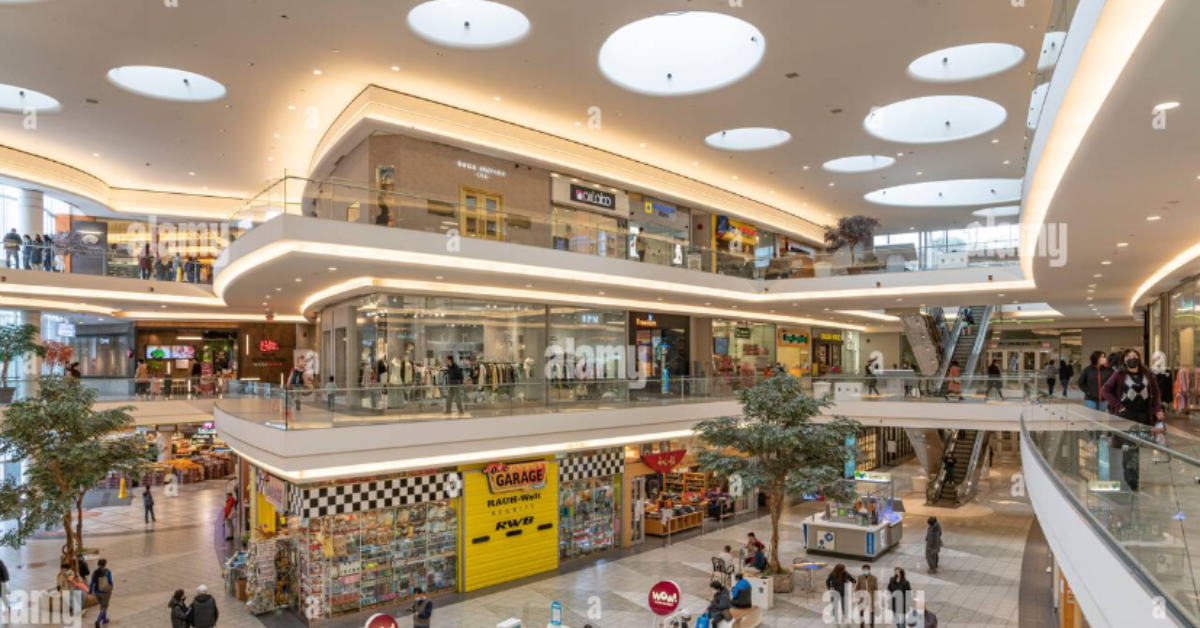
New retail space will drive nearly two-thirds of an expected 14-16% revenue growth of mall operators next fiscal, compared with a steady 10-11% foreseen this fiscal. Healthy preleasing should mitigate occupancy pressure as new supply comes onstream, while contractual rental escalations and mark-to-market gains on lease renewals will provide additional support to earnings. As a result, operating earnings should grow sufficiently to contain leverage despite a step-up in capital expenditure and borrowings, keeping credit profiles stable, according to Crisil Ratings.
Our analysis of 44 Grade A malls across 11 Tier 1 and 2 cities, with an aggregate retail area of around 37 msf and accounting for around half of India’s Grade A mall stock, indicates as much.
Retail area is expected to expand by 4.5-5.0 msf over this and next fiscal, more than double the addition in the preceding two fiscals.
Says Ankush Tyagi, Director, Crisil Ratings, “Preleasing is the key cushion against the occupancy pressure that typically accompanies rapid expansion. Around 70% of the space coming onstream this fiscal is already preleased, supporting a faster ramp-up of new malls. Portfolio occupancy should therefore remain healthy at 93-94% over this and next fiscal, as compared with 95-96% currently. As the new capacity ramps up, revenue growth should accelerate by 400-500 basis points next fiscal from 10-11% this fiscal, with nearly two-thirds of the growth coming from new additions. The expansion should thus strengthen earnings without weakening operating performance.”
Alongside new space, healthy consumption at existing malls should support revenue-share income, which accounts for 10- 15% of the overall revenue of mall operators. Mall consumption recorded healthy double-digit growth in the first quarter of this fiscal despite geopolitical uncertainties and disruptions. The growth was broad-based across categories, supported by overall economic growth and relatively contained inflation.
Sustained consumption growth should also provide headroom to reprice rentals as leases come up for renewal. With around 25% of mall operators’ area due for renewal over this and next fiscal, mark-to-market rental gains should complement contractual escalations and incremental income from new assets, providing multiple levers for revenue growth.
Delivering this expansion, however, will require a significantly higher investment outlay. Total capex is expected at around Rs 5,000-5,500 crore over this and next fiscal, compared with around Rs 2,500 crore in the preceding two fiscals. With the investment expected to be funded through debt and equity in a 1:1 ratio, debt is projected to rise by over 20% to around Rs 17,000 crore by next fiscal.
Says Pranav Shandil, Associate Director, Crisil Ratings, “Higher debt need not translate into weaker credit profiles if earnings keep pace. Rental growth at existing malls and incremental earnings from new assets should support Ebitda5 growth in line with borrowings. We therefore expect the debt-to-Ebitda ratio to remain broadly stable at 3.1- 3.3 times through next fiscal, compared with 3.1 times last fiscal, cushioning the credit impact of the investment cycle.”
The key risks to this balance are large debt-funded acquisitions that materially increase leverage and a sharp rise in interest rates. Higher rates could exert pressure on credit profiles through two channels: directly, by increasing borrowing costs and weakening debt service coverage ratios, and indirectly, by weighing on discretionary consumption, thereby affecting mall consumption and rental growth. These will remain key monitorables.