Subtotal ₹0.00


Email :12
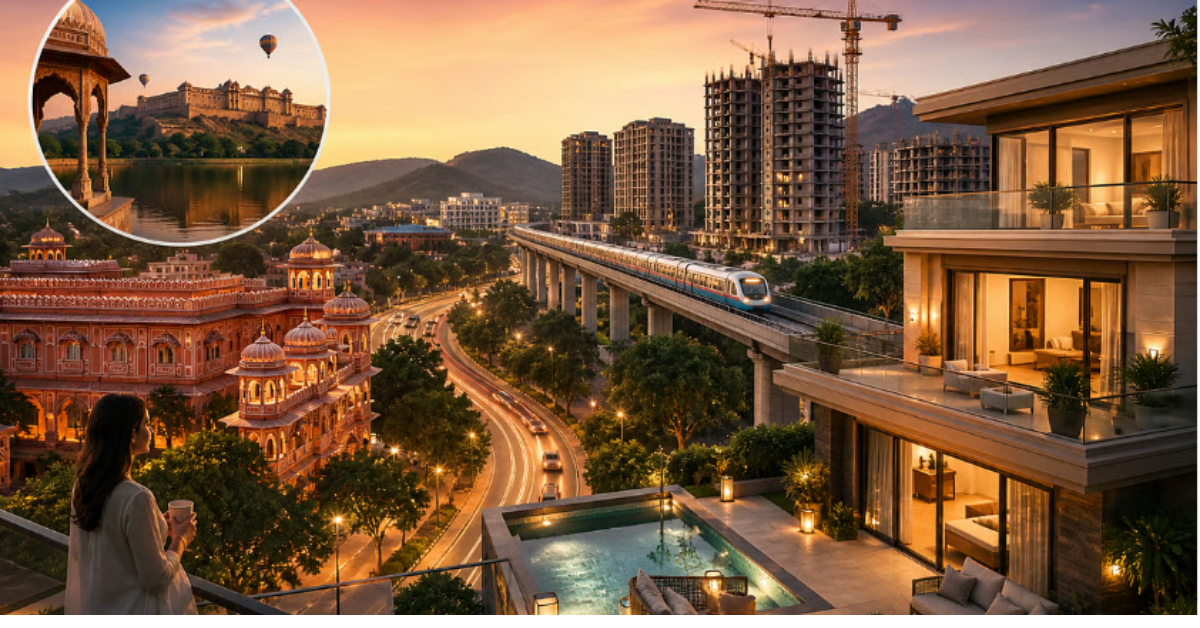
The Confederation of Indian Industry (CII) and Knight Frank India in their latest report – India’s Next Real Estate Markets, have identified India’s ‘next’ real estate markets, that have been identified through a multi assessment framework, having the potential of leading the next phase of real estate growth in India. These cities are recording faster residential price growth than India’s top eight cities, indicating a rise in momentum as their economic fundamentals continue to strengthen, backed by growth in infrastructure, connectivity and consumption.
The cities of Bhopal, Bhubaneswar, Chandigarh Tricity, Goa, Indore, Jaipur, Kochi, Lucknow, Nagpur, Visakhapatnam and Coimbatore recorded an average residential price CAGR of 8% between 2016 and 2026, compared with 4% across the top 8 cities. The gap has widened over the past five years, with residential prices across these 11 markets increasing by 63% between 2021 and 2026, as compared to 42% growth across the top 8 cities.
While the top eight cities will continue to anchor the sector given their volume, Tier-2 and Tier-3 cities are becoming increasingly important growth anchors. India’s real estate sector output is projected to reach USD 5.8 trillion by 2047, with Tier-2 and Tier-3 cities estimated to contribute 25–30 %, representing USD 1.4 –1.7 trillion in output. Realising this opportunity will require infrastructure that generates employment and enterprise, supported by demand-led formal supply, serviced land, efficient approvals, reliable utilities and liveable urban conditions.
he share of infrastructure expenditure in total government capital expenditure has increased from 39% in FY 2015 to 55% in FY 2026. As the government increases its commitment to infrastructure, the base for private capital has been fortified in the last decade leading to growing role of public-private partnerships. The government’s three-year PPP pipeline comprises of 852 projects with combined project cost of INR 17 lakh crores. Much of these projects will have long- term positive impact on the growth of tier 2 and tier 3 markets.
Shishir Baijal, International Partner, Chairman & Managing Director, Knight Frank India said, “India’s real estate growth is increasingly broadening beyond the traditional metropolitan centres. The investable opportunity across Tier-2 and Tier-3 cities, satellite markets and emerging corridors will be shaped not simply by infrastructure creation, but also by their ability to convert connectivity into sustained economic activity. Cities that bring together employment, enterprise, population growth, consumption and urban capacity will be better placed to build deeper and more diversified real estate markets. For investors and developers, this represents a wider opportunity landscape, but one that requires greater selectivity and a sharper understanding of each market’s underlying economic drivers.”
In 2025, key Tier-2 markets recorded 11.2 mn sq ft of warehousing lease transactions, broadly stable compared with 11.4 mn sq ft in 2024. Of these, the selected next real estate markets of Lucknow, Jaipur, Nagpur, Indore, Coimbatore and Bhubaneswar together accounted for nearly half of the total transactions in key Tier-2 cities, at 5.3 mn sq ft.
India’s retail footprint is also expanding beyond the major metros. The country had 134 mn sq ft of organised shopping-centre stock across 32 cities and 365 shopping centres in 2025, of which 36 mn sq ft was in 24 Tier-2 cities. The selected next real estate markets of Bhopal, Bhubaneswar, Chandigarh Tricity, Coimbatore, Indore, Jaipur, Kochi, Lucknow, Nagpur and Visakhapatnam together accounted for approximately 60% of the total Tier-2 shopping-centre stock.
India’s economic growth is becoming increasingly urban, with cities already contributing approximately 60% of national GDP while accounting for around 40% of the population (597 mn people). Globally, cities generate more than 80% of GDP despite accounting for around 45% of the population, underscoring the strong link between urban concentration and economic productivity. India’s urban population is projected to reach around 740 mn by 2050, while the number of cities with populations above one million, outside of top 8 cities, is expected to rise from 74 to 85.
Importantly, cities beyond India’s eight largest metros are projected to record population growth of around 28.2%, compared with 8.7% for the top eight, pointing to a widening geographic base of future economic activity. This expansion is being supported by a growing enterprise and employment ecosystem: MSMEs contribute around 31% of India’s GDP, 35% of manufacturing output and 49% of exports, while Tier-2 and Tier-3 cities account for around 50% of India’s more than 200,000 registered start-ups. Together, these trends indicate that India’s next phase of urban economic growth will increasingly be shaped by regional city-regions where enterprise, employment, incomes, consumption and infrastructure converge-creating the foundations for deeper and more diversified real-estate markets.
The emergence of these 11 markets marks a broader evolution in India’s real-estate landscape, with growth increasingly extending to city-regions that are building strong foundations across connectivity, employment, enterprise and consumption. As infrastructure improves and economic activity deepens, these markets are creating the conditions for more formal and diversified real-estate ecosystems spanning residential, retail, commercial and logistics assets. The opportunity ahead will therefore be shaped by how effectively these cities convert their economic potential into sustained urban development, making them an increasingly important part of India’s real-estate growth story and the country’s broader Viksit Bharat 2047 ambition.