Subtotal ₹0.00


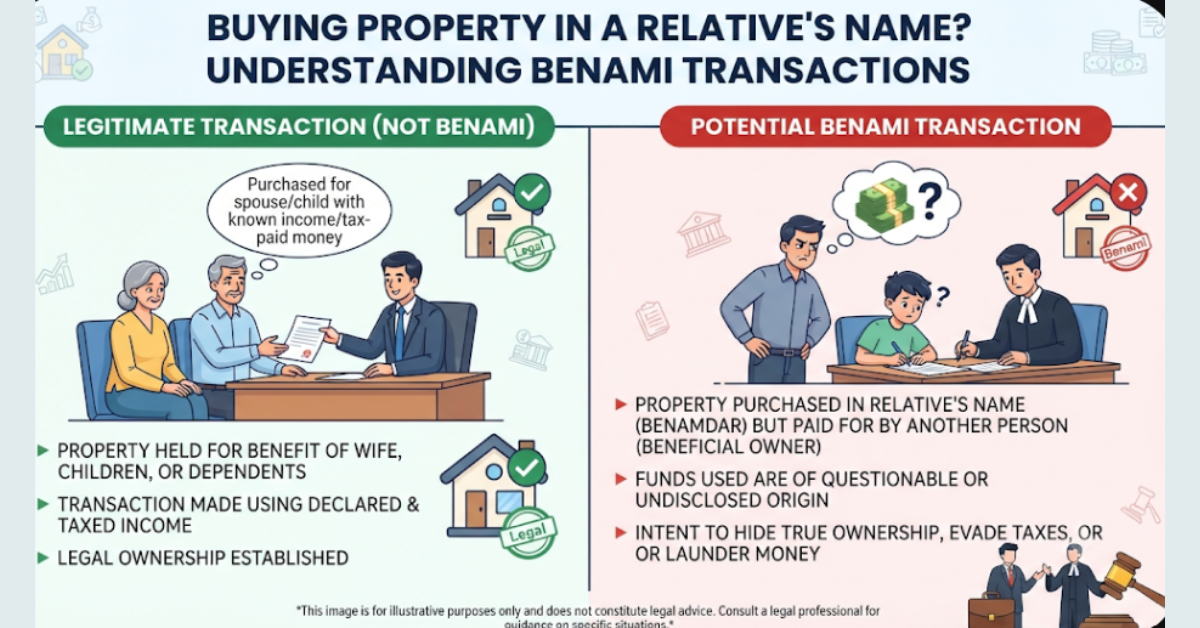
Buying a house in a spouse’s, child’s or parents name is not illegal in India. However, if the person paying for the property and the person named on the ownership documents are different, the arrangement could attract scrutiny under the country’s benami property laws.
The distinction lies in the source of funds, the intended ownership and who ultimately benefits from the property. A genuine family gift or a purchase that meets a specific statutory exception may be permitted. But using a relative’s name to conceal the actual owner or the source of money can have serious consequences, including attachment and confiscation of the property, according to a report by Business Standard.
The Prohibition of Benami Property Transactions Act, 1988, lays down specific exceptions for certain family transactions. These are conditional protections, not a blanket exemption for every property purchased in a relative’s name.
Under Section 2(9) of the Benami Act, a transaction can be treated as benami when one person pays for a property, another person holds its title and the property is intended to benefit the person who provided the money.
For instance, if a person purchases a house in a sibling’s name but continues to exercise ownership rights and receive rental income, the arrangement could attract scrutiny if it does not meet a statutory exception.
The authorities may examine:
- Who provided the money and whether the source can be established.
- Whether the registered owner had knowledge of the purchase.
- Who has possession and control of the property.
- Who receives rental income or other financial benefits.
- Whether the ownership arrangement is supported by legal documents.
Shaurya Mitra Tomar, senior partner at Chugh Universal Legal, said, “The law does not prohibit genuine property purchases within a family. What it seeks to prevent is the use of family relationships as a cover for undisclosed ownership, unaccounted funds or transactions intended to conceal the identity of the actual beneficiary.”
What are the exemptions for purchases in a relative’s name?
The Benami Act provides specific exceptions for certain purchases made using another person’s money.
An individual can purchase property in the name of their spouse or child using funds from their known sources. However, when buying in the name of a brother, sister, parent or child as a lineal descendant, the individual and the relative must both appear as joint owners in the property documents. The consideration must also come from the individual’s known sources.
Certain Hindu Undivided Family (HUF) property arrangements and fiduciary relationships also qualify for exceptions, subject to statutory conditions.
Rahul Hingmire, managing partner at Vis Legis Law Practice, cautioned that a family relationship alone does not provide protection.
“Kinship alone provides no blanket protection,” he said, adding that families must establish the substance of the transaction and satisfy the applicable statutory conditions.
A genuine gift is also different from an arrangement in which a relative merely lends their name while the person providing the money retains the beneficial ownership.
What happens if the source of money cannot be explained?
A property purchase can attract income-tax scrutiny if the investment cannot be explained through the buyer’s income, savings or other legitimate sources.
Under Section 103 of the Income-tax Act, 2025, which came into effect on April 1, 2026, an unexplained investment may be treated as the taxpayer’s income.
If authorities also establish that the transaction is benami, the property can be provisionally attached and, following adjudication, confiscated by the Central Government. Prosecution may also follow under the Benami Act.
Gautam S Thacker, advocate, Bombay High Court, said the Income-tax authorities may scrutinise the source of funds when a property is purchased in the name of a relative who does not have sufficient independent income.
“If the source of funds used to acquire the property cannot be satisfactorily explained, the Income-tax authorities may, subject to the applicable statutory requirements, treat the investment as unexplained and deem its value to be income of the person concerned,” he said.
What precautions should property buyers take?
Buyers should decide who will legally own the property and who will fund its purchase before signing the sale agreement. An informal understanding between family members may not be sufficient if a dispute or tax enquiry arises later.
Alay Razvi, managing partner at Accord Juris, said buyers should clearly establish whether the money provided by a relative is a gift, loan or contribution towards joint ownership.
He advised families to maintain records of the source and movement of funds, including bank statements, gift deeds, loan agreements and other supporting documents.
The following precautions can help:
Use banking channels:Make payments through identifiable bank accounts and avoid cash contributions or unexplained transfers through third parties.
Document gifts and loans: Execute appropriate gift deeds or loan agreements and retain evidence of the donor’s or lender’s financial capacity.
Register ownership correctly:If the intention is joint ownership, ensure that all intended owners are named in the registered sale deed.
Maintain financial records: Preserve bank statements, income-tax returns, loan papers and property purchase documents.
Record the arrangement at the outset: Do not wait until a tax notice, family dispute or investigation to explain who funded the purchase and why.
“Buyers should ensure that all funds are traceable through banking channels and consistent with the buyer’s income, savings, loans or documented gifts,” Razvi said.
Registering a property in a family member’s name requires more than trust between relatives. The source of money, legal ownership and actual benefits from the property must be consistent with the arrangement and applicable law.